
Family Bank Group has reported a 68% increase in profit after tax to Ksh6 billion for the nine months ended September 30, 2026, up from Ksh3.6 billion recorded during the same period last year, driven by growth in interest-earning assets and improved income generation.
The lender’s unaudited results show that total operating income rose 26% to Ksh18.6 billion, supported by a 37% increase in net interest income, while non-funded income stood at Ksh3.6 billion.
Total assets expanded 22% to Ksh247.5 billion, supported by a 14% increase in the customer net loan book to Ksh118.2 billion. During the period, the bank disbursed more than Ksh91 billion to the private sector, with over 70% directed towards micro, small and medium enterprises (MSMEs) and consumer banking.
Customer deposits grew 24% to Ksh182.3 billion, reflecting an expanding customer base that now exceeds 1.4 million accounts. Shareholders’ funds increased 29% to Ksh36.4 billion, while the bank’s liquidity ratio stood at 62%, well above the statutory requirement.
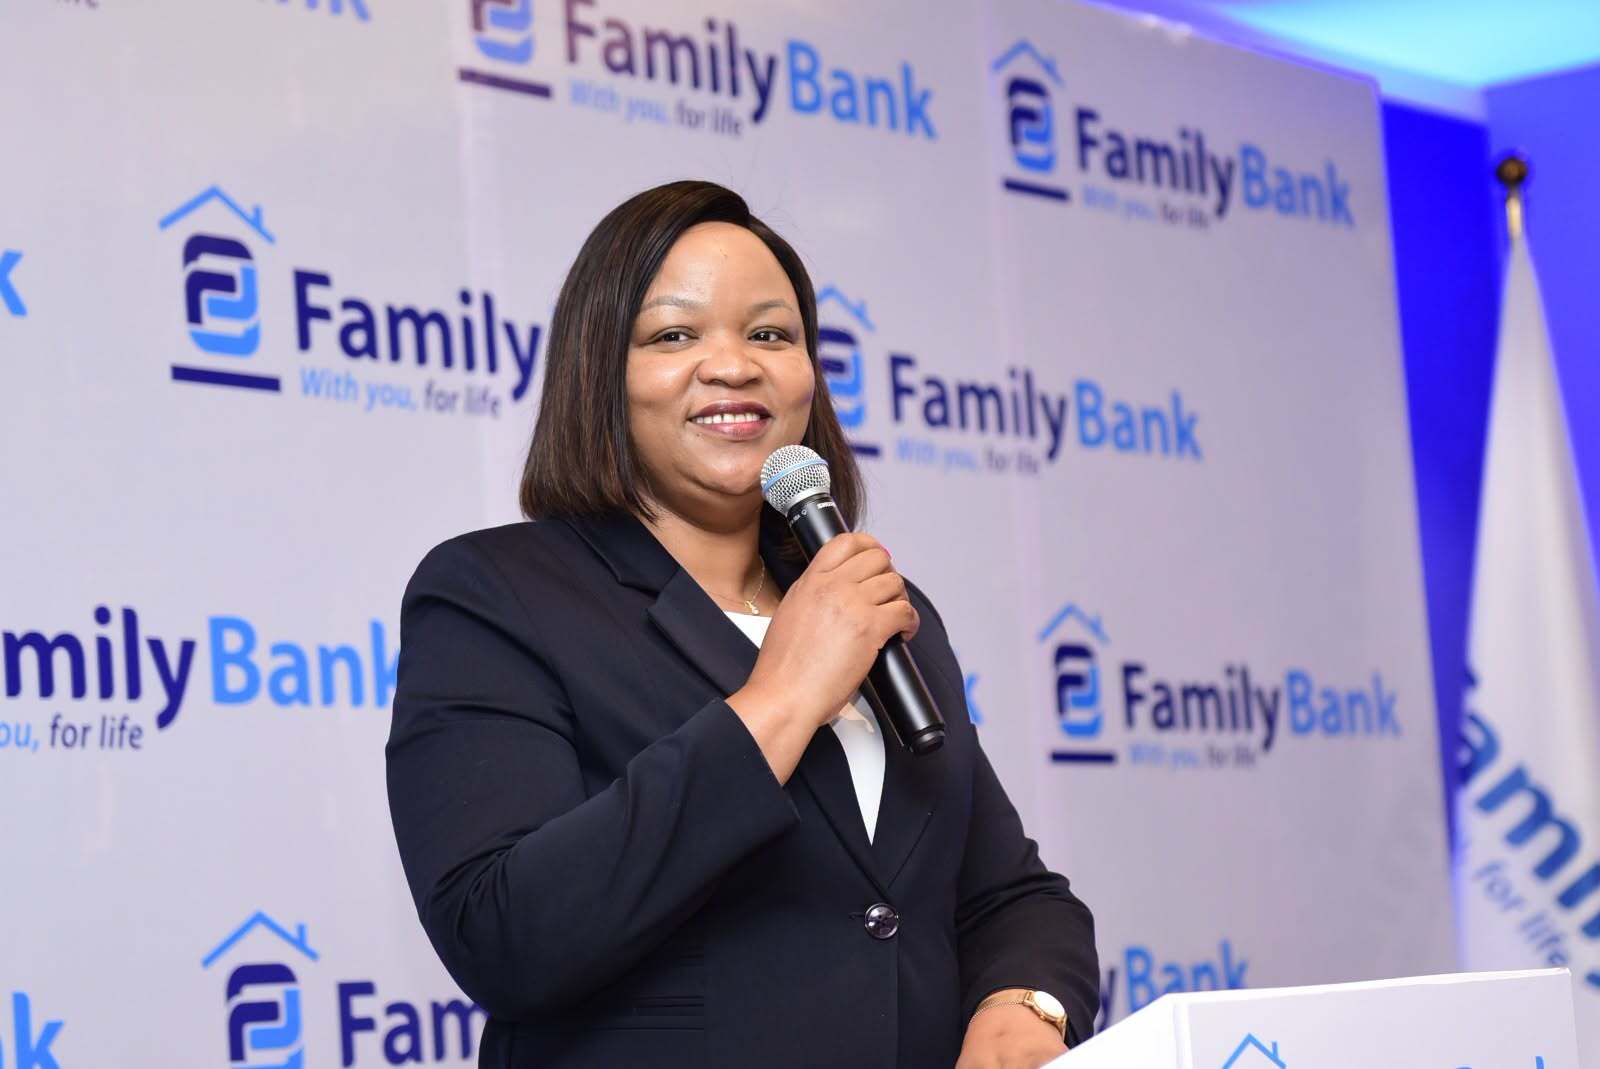
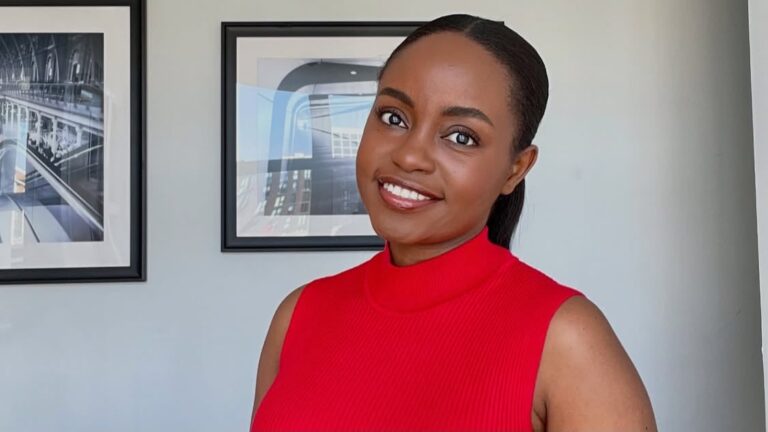
The results mark the bank’s first full quarterly reporting cycle since its listing on the Nairobi Securities Exchange (NSE) in June 2026, a milestone Chief Executive Officer Nancy Njau described as a turning point for the institution.
“These results reflect the strength and clarity of our strategy as well as the confidence our customers continue to place in us,” Njau said.
“Following our successful listing on the Nairobi Securities Exchange, we entered an important new chapter in the Bank’s growth journey, underpinned by a stronger commitment to transparency, accountability and long-term value creation for our shareholders.”
Njau said the lender would continue strengthening its presence across retail, MSME and commercial banking while investing in technology and expanding its distribution network.
“As we continue investing in our people, technology and distribution network, our focus remains on delivering innovative financial solutions and exceptional service across the Retail, MSME and Commercial segments, while building a resilient and sustainable Bank,” she added.
Family Bank’s performance in the first nine months of 2026 builds on growth recorded earlier in the year. The lender posted a 62% increase in profit after tax to Ksh3.7 billion for the first half of 2026, compared with Ksh2.2 billion during the corresponding period in 2025.
The half-year performance was supported by a balance-sheet strategy that saw net loans grow by 10%, while holdings in government securities increased 55% to Ksh94.1 billion. The bank benefited from returns on government securities while keeping funding costs nearly flat despite a 20% increase in deposits.
The June 2026 NSE listing transformed Family Bank from a privately held institution into a publicly traded company, subjecting it to increased disclosure requirements and shareholder scrutiny.
The listing followed years of preparation, including a 55% increase in full-year 2025 profit, when the bank’s total assets reached Ksh208.7 billion.
The development also coincided with the implementation of the bank’s 2025–2029 strategic plan, which focuses on expanding its customer base, growing retail and MSME lending, and investing in technology and branch network optimisation.
Despite the strong profit growth, the nine-month results revealed pressure on the bank’s asset quality. Gross non-performing loans increased to Ksh18.93 billion from Ksh15.60 billion a year earlier, prompting the lender to raise loan loss provisions by 27% to Ksh1.7 billion.
Operating expenses also increased 11% to Ksh11.4 billion, reflecting continued investment in technology, personnel and distribution infrastructure.
However, the bank’s capital adequacy ratios remained above regulatory thresholds, with total capital to risk-weighted assets standing at 18%, against the minimum requirement of 14.5%.
With three quarters of growth recorded, Family Bank enters the final stretch of 2026 with an expanded balance sheet, a broader shareholder base and a continued focus on MSME lending.
