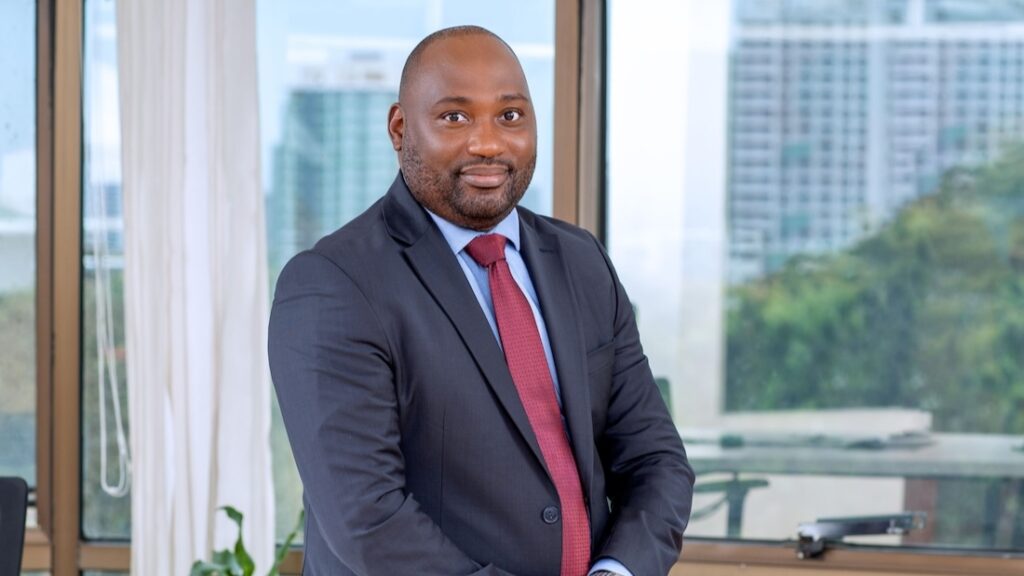
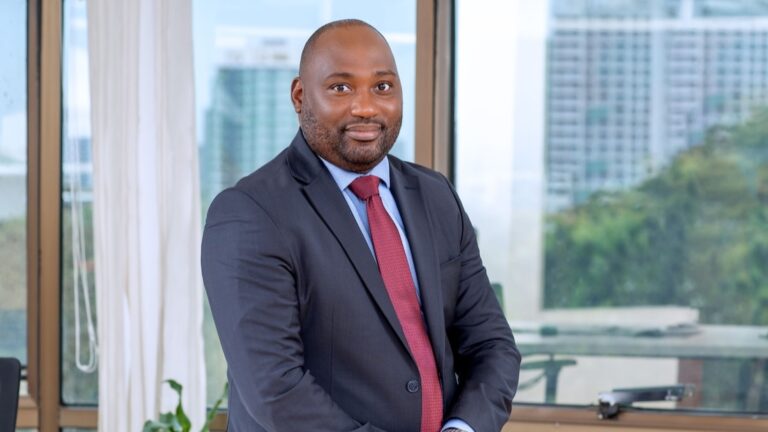
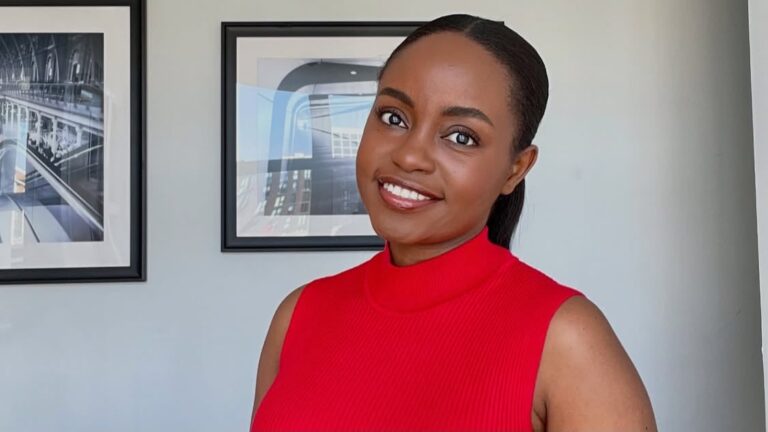
When Safaricom announced in November 2026 that Boniface Mungania would become its Chief Financial Services Officer, the press release told a tidy story of upward mobility: a customer care representative who joined in 2007 had risen, nearly two decades later, to lead the division that houses M-PESA.
The appointment was effective November 1, following regulatory approval, and placed him directly under the CEO.
The tidiness is accurate but incomplete. Mungania’s elevation is less a fairy tale of individual ambition than a case study in how Africa’s most consequential fintech platform reproduces its own leadership.
His career maps almost perfectly onto the evolution of M-PESA itself – from a customer-facing curiosity to a payments rail, then to a product ecosystem, and now to something Safaricom prefers to call a “techfin” platform rather than a fintech product.
The making of an operator
Mungania’s educational background was not obviously a prelude to a career in mobile money. He holds a Bachelor of Science degree from Jomo Kenyatta University of Agriculture and Technology, where he studied between 2002 and 2007.
According to one detailed account of his trajectory, he graduated in biochemistry and spent six months as a medical sales representative before joining Safaricom. The customer care desk was, in that sense, a pivot rather than a destination.
What followed was a deliberate accumulation of operational fluency. He moved from customer service into dealer management, then into M-PESA business development in 2011. By 2012 he was a Business Development Manager for M-PESA; by 2014, a Senior Manager.
A stint at Vodafone in Qatar as a mobile money consultant – reportedly recommended by then-CEO Bob Collymore – gave him exposure to diaspora remittance models and the mechanics of mobile money outside Kenya.
He returned to head M-PESA Product Management, then became Head of M-PESA Payments in April 2021, and later Payments Tribe Lead – a title that signaled Safaricom’s adoption of agile organizational language. The “tribe” nomenclature was not cosmetic. It reflected a shift toward cross-functional product teams and iterative deployment, a way of working that Safaricom has publicly credited Mungania with championing.
Then came a detour that turned out to be a credential. In April 2023, Mungania was appointed Director of Public Sector Digital Transformation, a role in which he oversaw the development of digital infrastructure – APIs, digital identity, national payment systems – and worked across agriculture, healthcare, MSMEs, and public finance. The work earned him the Order of the Grand Warrior (OGW), a state honour rarely bestowed on corporate executives.
That public-sector interlude matters for what came next. Safaricom’s financial services ambitions increasingly depend on government-adjacent infrastructure: identity systems, payment interoperability, subsidy distribution. Mungania had spent nearly three years learning how the state procures, adopts, and scales technology.
When Esther Waititu resigned as Chief Financial Services Officer in July 2026, Mungania stepped in as acting head before being confirmed in November.
The philosophy he brings
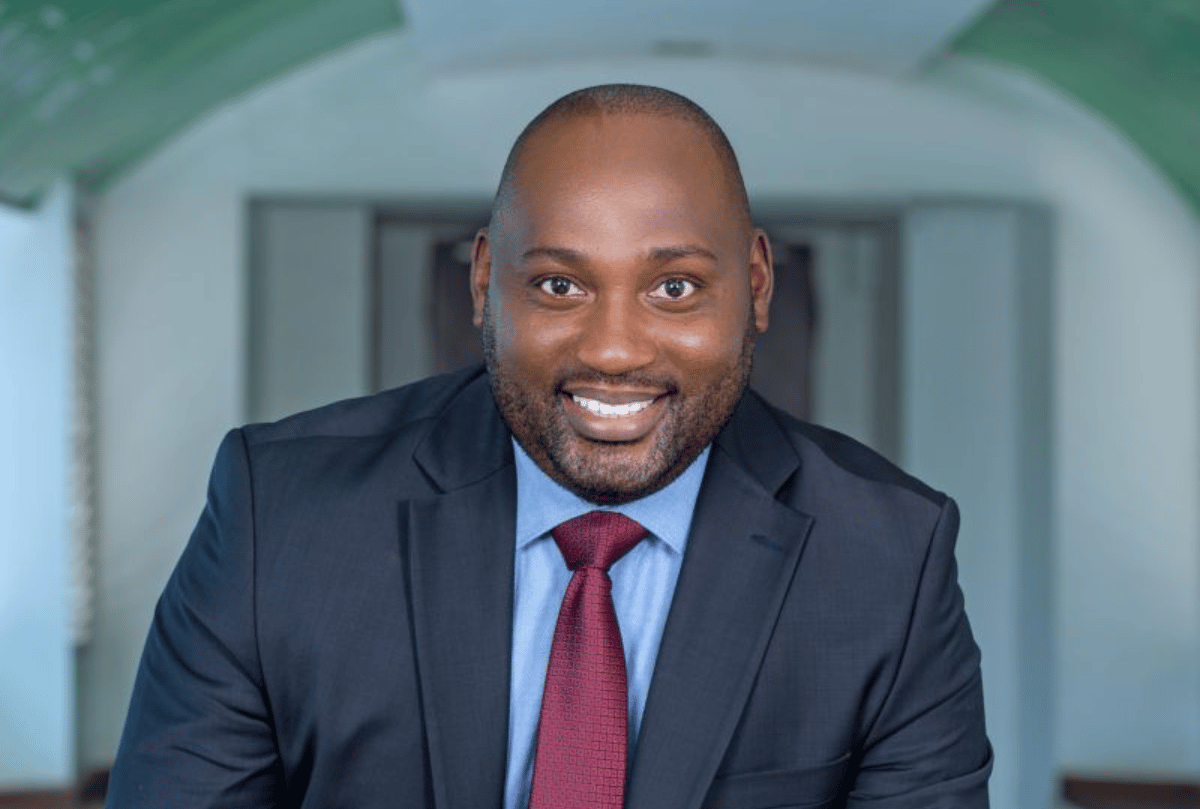
Mungania’s public statements suggest a product philosophy rooted in observed behaviour rather than theoretical segmentation. Speaking about the launch of Ziidi Sharia, a Shari’ah-compliant investment product, he framed inclusion as a matter of listening rather than engineering.
“Financial inclusion is not simply about making financial services available. It is about understanding the different realities of the people we serve. We listened to a segment of our population that felt left out of conventional products, and Ziidi Sharia is our response to ensuring holistic inclusion,” he said.
That rhetoric could be dismissed as corporate boilerplate, but it aligns with how Mungania has described the logic behind Fuliza, M-PESA’s overdraft facility. According to his account, Fuliza was not conceived in a strategy deck. It emerged from observing that customers’ transactions were failing because wallet balances were insufficient. Safaricom used that behavioural data to build an overdraft product. Fuliza facilitated Ksh1.15 trillion in lending during the six months to September 2026.
For Mungania, the significance of such products extends beyond revenue. He has argued that an overdraft enabling a trader to increase sales represents a more meaningful outcome than the platform’s financial performance alone.
Whether that customer-centric framing survives the pressures of a listed company’s earnings calls is an open question, but it is the framing he has chosen.
His view of M-PESA’s competitive position is equally distinctive. He describes the service as a “techfin”—a technology platform that enables financial services—rather than a financial services operation that adopted technology. The distinction has practical implications. Mungania does not expect M-PESA to replace banks and insurers.
Instead, he envisions financial institutions connecting their products to the platform and using its distribution capabilities to reach customers. That is a vision of M-PESA as infrastructure rather than competitor, a positioning that has become more urgent as regulators scrutinise market concentration and as banks build their own mobile channels.
The inheritance and the test
Mungania inherits a division that is both Safaricom’s growth engine and its most politically exposed asset. M-PESA processes a volume of transactions that makes it systemically important to Kenya’s economy. It is used for government disbursements, small-business payments, savings, insurance, and credit. Its reliability is a matter of public expectation, not just commercial reputation.
He also inherits the shadow of his predecessor. Esther Waititu, widely known as “Mama M-PESA,” was closely associated with M-PESA’s development during her tenure. Replacing a figure with that kind of symbolic weight is never administratively neutral.
Mungania’s advantage is that he is not an outsider trying to learn the culture; he has been inside it since before M-PESA was the dominant force it is today. His disadvantage is that he has never led the financial services division in a substantive, non-acting capacity until now.
The strategic questions are substantial. Competition in Kenyan digital payments has intensified, with banks, fintechs, and card networks all seeking to capture transaction flows that M-PESA has historically owned. Regulatory expectations around data protection, consumer protection, and interoperability have grown more demanding.
Safaricom’s expansion into Ethiopia introduces a new market where M-PESA’s model must be adapted, not replicated. And the lending portfolio – the Fuliza-led credit business – presents a dual imperative: extend access while maintaining loan quality.
Mungania’s background suggests he will approach these challenges through the lens of platform thinking rather than product competition.
In a 2026 interview about public-sector digital transformation, he described Safaricom’s approach as moving from bespoke solutions for individual contracts to building reusable infrastructure:
“From getting a contract to deliver solutions, to thinking DPI first, build the infrastructures that have too many use cases, and then do now the vertical solutions on top of that,” he stated.
That “DPI first” logic – digital public infrastructure as the foundation – translates naturally to financial services. Rather than building a new product for every customer segment, build the rails that allow many products, including third-party ones, to run. It is a vision of M-PESA as the operating system of Kenyan finance, not merely an app on a phone.
What the appointment signals
Safaricom’s decision to promote from within, and specifically to promote someone whose career began at the customer care desk, is a statement about institutional confidence. The company has long professed a commitment to internal talent development. In Mungania, it has a visible proof point: a biochemistry graduate who answered phones, learned the product from the ground up, went abroad, came back, ran payments, ran public sector, and now runs financial services.
Whether that narrative matters to the bottom line is debatable. What matters more is whether Mungania can do what the role now requires: hold together a platform that must be simultaneously commercially aggressive, politically attuned, and socially trusted.
M-PESA’s centrality to Kenyan life means its leader operates in a space where business decisions and public consequences are inseparable. The OGW on his CV suggests he understands that. The next few years will show whether he can act on it.
